Roof Insurance Claims in Murphy, TX
A roof insurance claim here often isn't the roof's first, and a second one turns on different evidence than a first one does.
You're deciding whether to file, and the deductible is half of that decision. Our roofers set the damage beside that number first.
What a Murphy roof claim turns on
Murphy Roofing Company sits on the homeowner's side of this one, so here's the part worth having before you call it in: the roof decides less about a claim than your policy does. Two lines on your declarations page and one old claim file settle most of it, and all three are worth reading before you file.
A covered event, with a date on it
Damage has to trace back to something your policy covers, on a day somebody can point to. Wear isn't an event, which is why pinning the storm matters as much as showing the damage does.
Replacement cost or cash value
Two houses can take the same hail and get very different checks, and that's usually down to this line. One policy pays what a new roof costs today; the other takes the roof's age off the top first and leaves you the difference.
The wind and hail deductible
It's separate from the everyday deductible on a lot of policies written for this county, and it's often a percentage of what the house is insured for. It's the number that decides whether you file at all.
What the last claim already paid for
On a repeat claim this one does more work than any of the others. Whatever an earlier settlement covered is money the carrier's already spent on that roof, so it sets what's still open to argue this time.
Cash value against replacement cost, explained
Two policies can look alike, cover the same storm, and settle nowhere near each other. The words to find on yours are replacement cost or actual cash value, and they decide whether the roof's age comes off the top.
Replacement cost pays what a new roof costs today, usually in two parts: a check up front, then the held-back depreciation once the work's finished and invoiced. Actual cash value pays once, with the years already subtracted, and that gap is yours to carry. On a roof that's been through a claim before, the difference bites harder, because the shingles are older than they were last time and the subtraction is bigger for it. Our roofers put the damage on record.
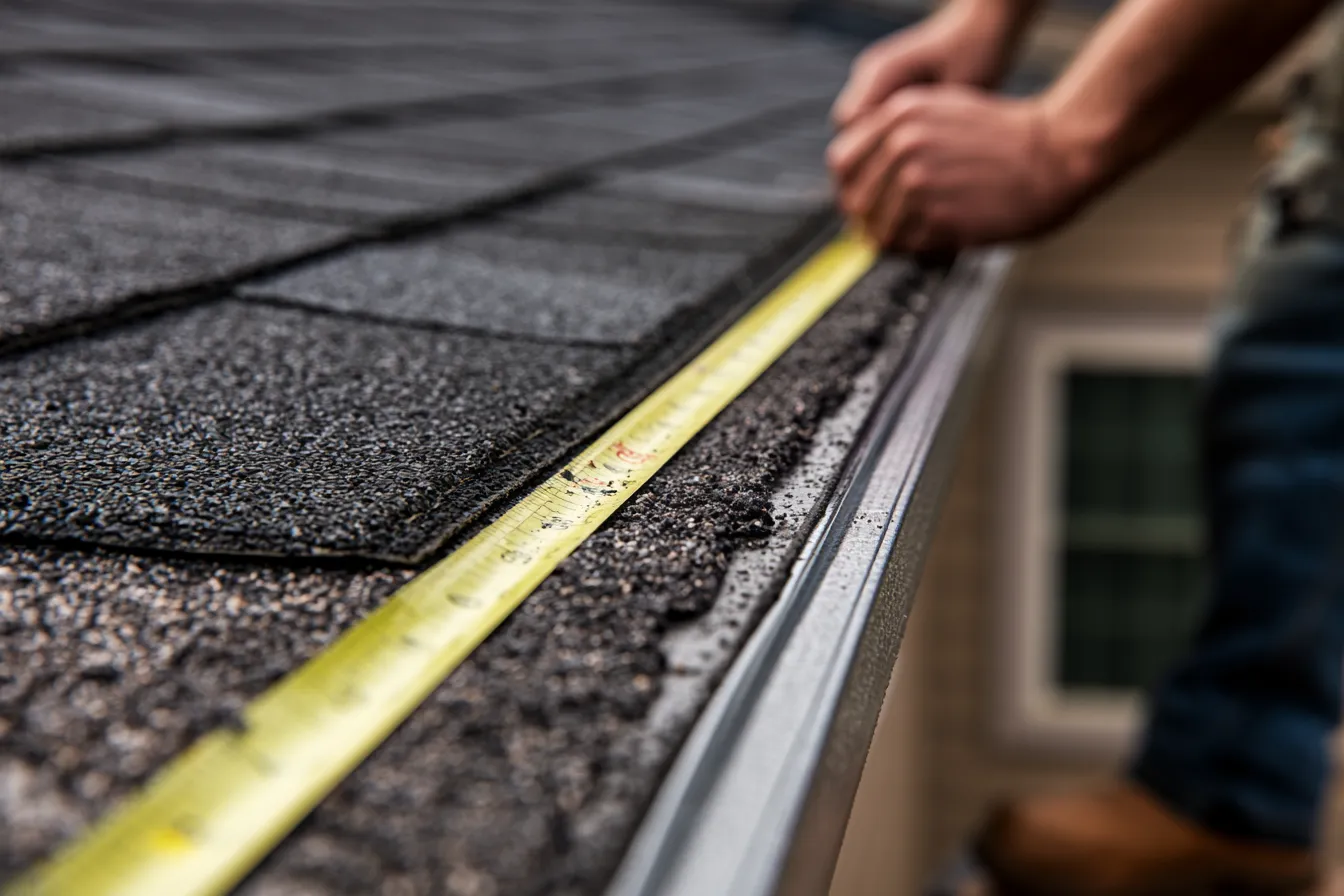
Photographs before there's a claim number
Your roofer photographs and measures before anybody calls it in, so what the carrier ends up looking at was recorded while the damage was fresh. Dated photographs are worth more six weeks later than anyone's memory of that week.
This storm told apart from the last
On a repeat claim the date does more work than the damage does, so your roofer lines the roof up against what the county recorded and when. That question comes standard on any roof with history behind it, and the file is built to answer it up front.
The earlier claim file, first
Anything a previous settlement paid for counts as already funded, so your roofer pulls that paperwork before taking a single new photograph. It's the document that decides what's still open this time around.
Cash value or replacement cost, named
Which one your policy uses moves the settlement further than any single patch of damage will, so your roofer says it out loud before anybody talks numbers. If you know which one you're holding, that first check reads very differently.
Your deductible, worked out early
Before any of this becomes a decision, the deductible goes next to what the damage is likely to cost, worked off your own declarations page. On a smaller loss that sum is the whole answer, and it is better known before a claim is open than after.
The file stays with you
Photographs, measurements and the write-up go where you go. The folder holds up whether the work ends up with the roofer who built it or with somebody else entirely.
A Murphy roof claim, start to finish
A claim runs longer than most people expect, and much of that stretch is spent waiting on other people rather than on anything happening up on the roof. What follows is the part you control.
The last claim's paperwork
What was replaced then, and when. On a second claim that one document shapes everything that comes after it.
Which storm you're claiming
A date the county record backs up, matched to what the roof shows. Damage nobody can date is what you'll end up arguing about.
The roof, the ceilings, the yard
Soft metal, ceiling stains and whatever sits at ground level with fresh marks on it. Half the useful evidence on a hail claim never comes off the roof at all.
Your declarations page
Cash value or replacement cost, the wind and hail deductible, and the window the policy gives you to report it. Ten minutes on that page with your roofer changes what you do next.
And the claim stays yours
Our roofers can work with the adjuster so nothing on the write-up goes unexamined. The policy is yours, the decision is yours, and so is the file behind it.
What people ask when filing a claim
Get Murphy damage documented for a claim
Old claim paperwork, the storm date, and whatever you photographed at the time: that's what a local roofer builds a claim file around. If you can't place which storm it was, the county storm record narrows it down fast.